
FD Investors Take Note: RBI's New Deposit Rate Rules From October 1, 2026
RBI's New FD Rules: What Changes From October 1?
Fixed deposit investors are set to see a change in the way banks disclose and manage deposit interest rates from October 1, 2026.
The Reserve Bank of India (RBI) has revised its framework governing interest rates on deposits. The updated rules place greater emphasis on transparency in deposit-rate disclosures while also introducing changes affecting the pricing of certain bulk deposits.
For ordinary retail FD investors, however, the most important point is that the new rules do not mean every FD interest rate will automatically change from October 1.
Instead, the revised framework changes how banks disclose rates and provides a more structured approach to pricing certain large deposits..
What Has RBI Changed?
The revised framework covers deposit interest rates offered by various categories of banks and introduces clearer requirements around the disclosure and application of those rates.
Three areas are particularly relevant:
- Disclosure of deposit interest rates
- Uniformity in rates for similar deposits
- Revised provisions for bulk deposits
These changes are intended to make deposit pricing more transparent while allowing banks greater flexibility in managing large deposits..
1. Banks Will Have to Disclose Deposit Rates Clearly
One of the key changes concerns the disclosure of interest rates, particularly for bulk deposits.
Under the revised framework, banks must make applicable bulk-deposit rates available on their websites at the beginning of each business day.
For bulk deposits, the applicable rates are required to be disclosed by 10:00 AM, with a 10-minute grace period..
For customers placing large sums with a bank, this creates a clearer reference point when comparing the rate offered with the rate publicly disclosed by the institution.
The move is particularly relevant for businesses, institutions and high-value depositors dealing with large deposits..
2. Similar Deposits Should Receive Uniform Treatment
The revised RBI framework also strengthens the requirement for banks to maintain uniformity in deposit interest rates.
For deposits of a similar amount accepted on the same date and under the same applicable conditions, banks cannot simply offer different rates based on the branch or customer.
For retail investors, this can make it easier to compare the rate quoted by a bank with its officially published deposit-rate schedule.
It also reduces uncertainty around whether the rate being offered is consistent with the bank's disclosed terms.
3. New Provisions for Bulk Deposits
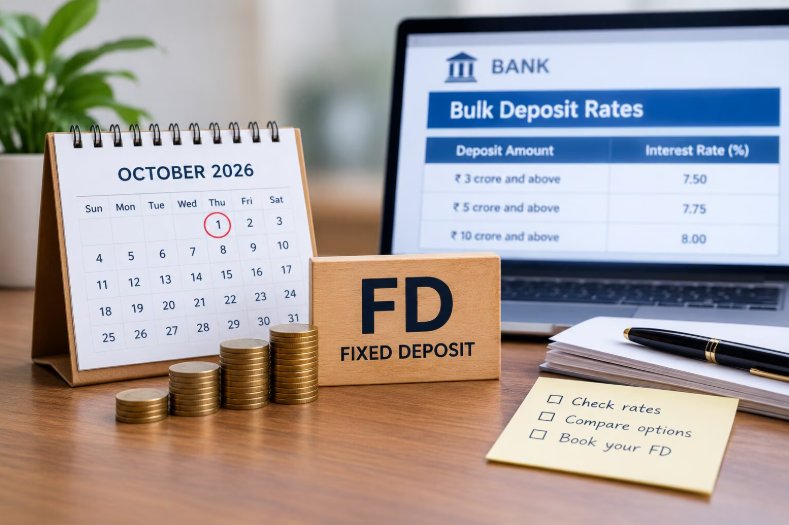
Bulk deposits are an important part of the revised framework.
For scheduled commercial banks, the bulk-deposit threshold is generally ₹3 crore and above.
This means the bulk-deposit provisions are mainly relevant to customers placing very large amounts rather than the typical individual investor opening an FD with a few lakh rupees.
The revised framework gives banks greater flexibility to offer differential interest rates on eligible bulk deposits by taking into account liquidity considerations under the Liquidity Coverage Ratio (LCR) framework.
For large depositors, therefore, comparing the published rate and understanding the applicable conditions becomes particularly important.
Will Your Existing FD Interest Rate Change?
Not automatically..
This is perhaps the most important clarification for ordinary FD holders.
The RBI's revised rules do not instruct banks to change every existing FD rate from October 1.
If you already have a fixed deposit with a predetermined interest rate and tenure, the new framework does not by itself mean that the contracted rate will suddenly change on October 1.
The impact is more relevant when you are opening a new deposit or dealing with a deposit that falls under the revised bulk-deposit provisions..
What Does This Mean for Retail FD Investors?
For most retail investors, the immediate impact is likely to be greater transparency rather than a direct change in returns.
If you are planning to invest ₹1 lakh, ₹5 lakh or ₹10 lakh in an FD, you should continue comparing the bank's current rates and terms before making a decision.
Important factors include:
- Interest rate
- Deposit tenure
- Senior-citizen rate, where applicable
- Premature withdrawal conditions
- Interest payout frequency
- Tax implications
- Deposit insurance coverage
- Overall terms offered by the bank
The RBI's new framework does not eliminate the need to compare FD products.
Does RBI's New Rule Mean FD Rates Will Increase?
No.
The October 1 changes should not be interpreted as an RBI order requiring banks to increase FD interest rates.
Banks continue to determine their deposit rates within the regulatory framework and based on their funding requirements, market conditions and other factors.
Therefore, the implementation of the new rules does not guarantee higher FD returns.
Similarly, investors should not assume that every bank will reduce its FD rates because of the new framework.
Why Are Bulk Deposits Getting Special Attention?
Large deposits can have a significant impact on a bank's liquidity position.
The revised framework takes this into account by allowing eligible bulk deposits to be priced with greater consideration of their liquidity characteristics under the LCR framework.
For a large depositor, even a small difference in the interest rate can have a substantial impact on total interest income.
That makes the RBI's new disclosure requirements more relevant for high-value deposits than for ordinary retail FDs..
What Should FD Investors Do Now?
Retail investors do not need to make a decision simply because the rules take effect on October 1.
If you are planning to open a new FD, check the bank's official website for its latest interest-rate schedule and compare the available tenures.
If you are placing a large deposit, pay closer attention to the bank's bulk-deposit rates and the conditions attached to them.
Investors should also avoid looking at the interest rate alone. Liquidity requirements, premature withdrawal rules, taxation and the financial institution itself can all influence whether a particular FD suits their needs.
October 1 FD Rule: What You Need to Remember
The RBI's revised deposit-rate framework can be summed up in a few points:
The rules take effect from October 1, 2026.
Banks will have stronger disclosure requirements for deposit interest rates, particularly for bulk deposits.
Similar deposits are expected to receive uniform interest-rate treatment under the applicable conditions.
Bulk deposits receive revised pricing provisions linked to liquidity considerations.
The new rules do not automatically change every existing retail FD rate.
Retail investors should continue checking the latest rate and terms before opening a new FD.
The Bottom Line
RBI's new deposit-rate rules from October 1, 2026, are primarily aimed at improving transparency and creating a more structured framework for bank deposit pricing.
For large depositors, the changes around bulk-deposit rate disclosure and pricing could be particularly relevant. For ordinary FD investors, however, the new framework does not mean that every existing FD will suddenly get a new interest rate.
If you are planning to open an FD after October 1, compare the bank's latest published rates, tenure options and withdrawal conditions before investing.
As deposit rates can change over time, always verify the latest terms directly with the respective bank before making a financial decision.
This article is for informational purposes only and does not constitute financial advice.